Life insurance advice from real people.
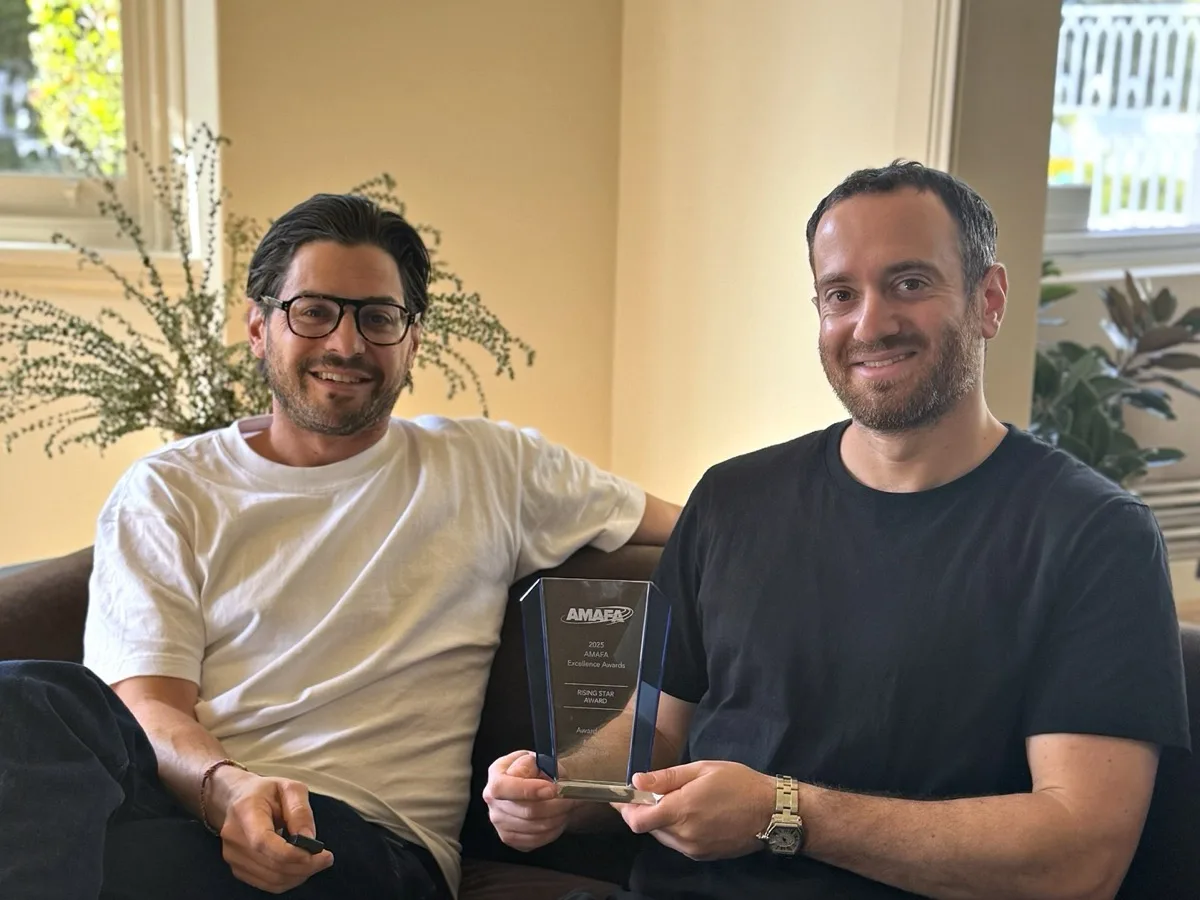
Right: our principal adviser, AMAFA Risk Adviser of the Year 2026, with his 2025 Rising Star trophy (AMAFA is our licensee, AFSL 389206). Both founders: 2026 ifa finalists.
Not an online form, a call centre or an algorithm. One adviser compares major Australian insurers and stays with you through every claim.
Not an online form, a call centre or an algorithm. One adviser learns your situation, compares a panel of major Australian insurers, and stays on it through underwriting and every claim. When something goes wrong, you call a person who already knows your story, not a queue that asks for your policy number.
No-obligation. We are paid by commission from the insurer, already built into the premium. If a fee applies, we tell you up front.
Award-winning adviser. Two 2026 ifa Excellence Awards finalists on our team.Our principal adviser: AMAFA Risk Adviser of the Year 2026, Rising Star 2025, ifa Risk Adviser of the Year finalist. Our co-founder: ifa Innovator of the Year finalist. Pictured together with the 2025 Rising Star trophy. AMAFA is also Safety Nest’s licensee (AFSL 389206).
We advise across major Australian insurers


What clients say
Real clients on what it was like to work with us.
Safety Nest's recent social media marketing campaign caught my attention for the simplified approach to getting Life Insurance, so I reached out to start the discussion I'd been putting off. My onboarding interactions were seamless and everything was drilled down and explained so well that the hard work was taken off my hands. Hassle free, professional and secured me a great result. Highly recommend them. Their online portal is also really easy to view, interact with and make changes against.
Finding a trustworthy insurance provider was important to me, and Safety Nest did not disappoint. They were clear, honest, and took the time to understand what I was looking for. I appreciated that they didn't try to upsell me, but rather focused on what would actually benefit my family. Highly recommended!


The honest comparison
Why use a personal risk insurance adviser?
There are three ways Australians get life insurance: buying direct online, the default cover inside super, or through a personal risk insurance adviser. Here is how they compare, question by question.
| Going direct / online | Cover in super | Personal risk insurance adviser | |
|---|---|---|---|
| Getting accepted | You apply and take whatever terms come back. | Automatic, but on limited group terms. | We can test insurers quietly first, before you commit. |
| If you ever claim | You deal with the insurer on your own. | You go through the fund, which can be slower and harder. | We assist with claim documentation and communication with the insurer. All claims remain subject to the applicable policy terms and the insurer’s assessment. |
| What it costs you | The premium, sometimes plus a fee. | Premiums deducted from super reduce the amount remaining invested for retirement. | Commission inside the premium, any fee agreed up front. |
| Who compares insurers for you | Not compared for you; you pick the insurer and amounts yourself. | Not compared; one group policy chosen by the fund. | We compare a panel of major Australian insurers for you. |
| The advice you get | General advice only, issued without a check that the cover suits your circumstances. | No personal advice. A default amount that may not reflect your income, debts or dependants. | Personal advice built around your health, income and family. |
| As life changes | Typically not reviewed as your circumstances change. | Typically not reviewed as your circumstances change. | Reviewed each year as your life changes. |
The honest comparison
Why use a personal risk insurance adviser?
There are three ways Australians get life insurance: buying direct online, the default cover inside super, or through a personal risk insurance adviser. Here is how they compare, question by question.
Getting accepted
We can test insurers quietly first, before you commit.
Going directYou apply and take whatever terms come back.
Cover in superAutomatic, but on limited group terms.
If you ever claim
We assist with claim documentation and communication with the insurer. All claims remain subject to the applicable policy terms and the insurer’s assessment.
Going directYou deal with the insurer on your own.
Cover in superYou go through the fund, which can be slower and harder.
What it costs you
Commission inside the premium, any fee agreed up front.
Going directThe premium, sometimes plus a fee.
Cover in superPremiums deducted from super reduce the amount remaining invested for retirement.
Who compares insurers for you
We compare a panel of major Australian insurers for you.
Going directNot compared for you; you pick the insurer and amounts yourself.
Cover in superNot compared; one group policy chosen by the fund.
The advice you get
Personal advice built around your health, income and family.
Going directGeneral advice only, issued without a check that the cover suits your circumstances.
Cover in superNo personal advice. A default amount that may not reflect your income, debts or dependants.
As life changes
Reviewed each year as your life changes.
Going directTypically not reviewed as your circumstances change.
Cover in superTypically not reviewed as your circumstances change.
Not sure which of the three you are actually on?
Start HereGeneral information only. It compares typical features and does not take your personal circumstances into account. Individual situations vary, and default cover in super suits some people. A review can confirm what is right for you.
How we get paid
No catch, no separate advice fee
This is the question we are asked most, so we answer it plainly. We are paid a commission by the insurer, and it is already inside the premium you would pay anyway. Your advice, application help, claims support and yearly reviews are all part of it, and covered by that commission.
Commission rates are capped and regulated. Because commission is a percentage of the premium, the amount we receive still varies between insurers and policies, which is a conflict of interest we are required to manage and disclose. We will tell you the commission on any policy we recommend before you decide anything.
What you pay
The commission is already inside your premium
Paid by the insurer, included in the price. Your advice, application help, claims support and reviews are part of it.
Cover suited to your circumstances
Comprehensive insurance solutions for your peace of mind
Personal risk cover, advised and tailored to your situation. We help you arrange suitable protection across every stage of life, and review it as your needs change.
How it works
How to get started with Safety Nest
Follow these simple steps to book a consultation call and get started with protecting your future. Our advisers will guide you through the process and help you consider an appropriate level and type of cover.
No Obligation Online Consultation
Schedule a consultation call with one of our experienced insurance advisers over Zoom or Google Meet.
Fact-find first, then advice in writing
On the call we ask about your objectives, financial situation and needs. Nothing is recommended on the call: if you want advice, we research it and give you any recommendation in writing before you decide anything.
Application & Underwriting
If you decide to go ahead, we help you apply and guide you through underwriting. Cover is subject to the insurer’s terms and acceptance.
For your profession
Cover that understands how you actually work
The right definitions, the right income protection, the right application. What matters is not the same for a surgeon, a barrister, a chippie or a FIFO worker. Whatever you do, we quote cover matched to how your work pays and what puts it at risk. The ones below are just a few examples.
Real stories, real protection
Families and business owners who sleep easier
The smooth, personalised support from the Safety Nest team made the entire process easy. They carefully considered our unique situation and ensured we had a plan that made us feel secure about protecting our family’s future. We now have full confidence that we’re prepared for whatever comes next.
Before switching to Safety Nest, we rarely heard from our previous advisor and didn’t realise how much I was overpaying. The team at Safety Nest took the time to thoroughly review our situation, and I found out we could save thousands of dollars a year. Their personalised approach and regular check-ins gave us peace of mind, knowing our family’s future is now secure and well-managed. (Individual results vary; not a typical or expected outcome.)
Client stories are individual experiences and are not a typical or expected outcome. General information only, not personal advice.
FAQs
Find answers to common questions
Everything you need to know about consultations, policies and how our advice works.
Still have questions?
Contact usWhat types of personal insurance does Safety Nest offer?
How can I book a consultation with an adviser?
How is the initial consultation paid for?
What if I already have insurance?
How long does a consultation typically take?
How long does it take to set up insurance coverage?
How much does risk insurance cost?
How much does Safety Nest charge?
Protect your future
Protect your family's financial future
Talk to our advisers about your insurance options. We offer flexible times, so book your no-obligation online consultation today and start planning for tomorrow.